
Key takeaways
• Retail video analytics in 2026 is a KPI dashboard, not a surveillance product. Shrinkage, queue abandonment, planogram compliance, on-shelf availability, conversion — the store network is asking business questions, not looking at video walls.
• Self-checkout shrinkage changed the math. Published loss multiples run from ECR’s ~1.45× on whole-store shrink to Grabango’s 16× on lane-level loss rate, depending on what gets measured. It’s the single biggest reason retailers are writing fresh video-analytics RFPs this year.
• Privacy-by-design wins the compliance review. Skeleton / keypoint analytics, anonymized demographic brackets, on-device inference, 30–90 day retention: all of it survives BIPA, CCPA, GDPR, and the expanding list of municipal facial-recognition bans.
• Edge-first, cloud-aggregated is the default architecture. Jetson-class inference per store, metadata upstream to a chain-level dashboard. Retail bandwidth is bad; don’t ship raw video over the WAN if you can avoid it.
• A 50-store rollout pays back in 11–15 months for most retailers. Start with shrinkage + SCO loss, layer planogram and queue management in phase two. Don’t try to ship everything at once.
Updated October 2026: per-store hardware and the 50-store ROI re-priced after NVIDIA’s July 2026 Jetson price rise (payback now 11–15 months), the FCC’s July 2026 import ban on previously authorised covered cameras, and a straight answer on cost per store per month.
Why Fora Soft wrote this retail playbook
Fora Soft is a software development company that has built video surveillance and AI products since 2005 — 250+ shipped projects with a 50+ person in-house team. Our video surveillance practice and AI integration team ship VMS plugins, edge inference stacks, and ONVIF-based analytics pipelines for security integrators and retail-tech product companies. Valt, our long-running video surveillance product, now serves 770+ US organizations and 50,000+ users across law-enforcement, research, and enterprise environments; those engineering patterns map cleanly to retail.
This playbook is written for retail CIOs, heads of loss prevention, retail tech product leads, and systems integrators who already sell into retail. It answers the questions we hear on every scoping call: what’s real versus hyped in 2026, which KPIs the platform actually has to move, how edge inference and cloud aggregation split the work, how to pass privacy review in the US and EU, and what a realistic 50-store rollout looks like on a quarter-by-quarter basis.
Scoping retail video analytics for your chain?
30 minutes with a video engineering lead who’s shipped this into multi-site retail. Bring your store count, your VMS / POS stack, and your compliance envelope.
What is retail video analytics, and what does it cost per store?
Retail video analytics is software that runs computer-vision models on a store’s IP cameras and turns the footage into business metrics: foot traffic, conversion, queue depth, dwell time, shelf compliance and self-checkout loss. Store, loss-prevention and category teams act on those numbers instead of watching video. In a 2026 deployment the models run on an edge box inside each store, and only the metrics travel to a chain-level dashboard.
Retail video analytics vs. retail analytics software. Retail analytics software is the wider category: tools that analyse POS, e-commerce, inventory and loyalty data for dashboards, forecasting and pricing. Video analytics is the in-store sensor layer that feeds it with what transactions cannot see — how many people walked in, where they stopped, how long they queued, which facings were empty. Both land in the same warehouse, and that is where store conversion comes from: POS transactions divided by video-counted visitors.
| Retail analytics software | Retail video analytics | |
|---|---|---|
| Data source | POS, e-commerce, inventory, loyalty | Store cameras (plus POS for scan-sync) |
| Answers | What sold, where, at what margin | Who came in, queued, browsed, walked off; what’s missing on the shelf |
| Runs | Cloud / data warehouse | Edge box per store, metrics to the cloud |
| Main buyers | Merchandising, finance, e-commerce | Loss prevention, store ops, category management |
Cost per store per month. In the 50-store model further down, software and SaaS licensing runs $100–200 K a year, which is roughly $170–$330 per store per month. On top of that sits $9–13 K of one-off camera and edge hardware for a grocery or big-box store at October 2026 prices ($5–9 K for an 8-camera specialty store) plus integration work. Amortise the hardware over five years and the all-in run rate from year two is about $450–$750 per store per month. These are planning ranges from our own scoping, not vendor quotes.
Can it use the cameras you already have? Usually yes, if they are 2 MP or better IP cameras with an ONVIF profile. Analog fleets need encoders and lose the shelf-level detail; the hardware section below covers where a partial refresh pays off.
What changed between 2023 and 2026
Three structural shifts made retail video analytics a board-level topic. First, the shrinkage crisis. The National Retail Federation’s last full National Retail Security Survey, its 32nd, put FY2022 US shrink at $112.1 B, about 1.6 % of sales. NRF then retired that 32-year survey in 2024 over methodology concerns and now reports theft separately; its 2026 Impact of Retail Theft & Violence survey (66 retailers, 143 brands, $1.7 T of 2025 sales) recorded a 12.4 % decrease in shoplifting incidents and an 8.1 % drop in merchandise theft between 2024 and 2025, while repeat offenders, ORC incidents and walkout theft all rose. In that report, released 30 July 2026, 37 % of retailers saw more walkout or push-out theft and 63 % reported fewer than half of store theft incidents to police, which is why chains want their own measured loss data rather than police statistics. Read the headline dollar figure as directional, not gospel. The loss is real, and it concentrates in predictable places.
Second, self-checkout rewrote the loss math. Grabango’s computer-vision study of ~5,000 transactions (2023) found 6.7 % of SCO transactions carry at least partial shrink against 0.32 % at staffed lanes. That is transaction incidence, roughly 21×; the same study’s revenue-basis rates (3.5 % against 0.21 %) are where the widely-quoted 16× comes from. ECR Retail Loss’s Self-checkout Loss Report 2026 puts SCO loss at 28.5 % of all business loss for one contributing retailer, up from the 9.4 % Beck measured in 2018. Retailers didn’t walk away. ECR reports 96 % of grocery and 77 % of non-grocery retailers already run some form of SCO, so the fix isn’t ripping it out. It’s wrapping the lane in computer vision.
Third, the privacy regime both tightened and sharpened. Illinois amended BIPA in August 2024 (SB 2979) to cap damages at a single per-person recovery, defusing the old per-scan “annihilative liability” math. Consent is still mandatory, though, so a face-template database stays legally radioactive in Illinois. The EU AI Act’s prohibitions took effect 2 February 2025, including biometric categorisation that infers sensitive traits such as race, religion or sexual orientation. The high-risk tier moved: the AI Omnibus entered force 27 July 2026 and pushed Annex III obligations out to 2 December 2027, which buys retail programmes time but changes nothing about the February 2025 red lines. Add the municipal face-recognition bans (San Francisco 2019, Portland 2020) and one design choice falls out: anonymized skeleton / keypoint analytics — the same primitives behind fall detection and behavior analysis — become the default architecture.

Figure 1. Self-checkout concentrates the shrink — 6.7 % of SCO transactions show partial shrink against 0.32 % at staffed lanes on a transaction-incidence basis (Grabango, 2023), the exact metric a computer-vision scan-sync layer is built to move.
The retail KPIs video analytics actually moves
Retail buyers don’t buy cameras. They buy numbers on a dashboard. The numbers that matter:
1. Shrinkage rate. Industry average ~1.6 %; every 0.1 point of shrink is roughly $1 M a year on a $1 B sales base. A well-tuned video analytics pipeline credibly takes 0.2–0.4 points off that.
2. Conversion rate. Foot traffic counted at the door vs. transactions at the POS. Video gives you the denominator; POS gives you the numerator. Without both, you’re guessing.
3. Queue abandonment. Nobody has a credible industry-wide dollar figure for baskets abandoned at the lane, so don’t buy one from a vendor deck. Instrument your own: carts leaving the queue zone against completed transactions, by daypart. Real-time queue depth triggers dynamic staffing — the single highest-ROI operational feature in most deployments.
4. Dwell time by zone. How long customers spend in produce, electronics, or a promotional end-cap. Correlates with basket size; the raw material for merchandising decisions.
5. Planogram compliance. Share of shelf sets matching corporate standards. Vendor-reported category lifts cluster at 3–5 % on fully compliant sets; nobody has published a controlled study, so measure your own baseline before you budget against it.
6. On-shelf availability (OSA). Share of SKUs actually present in their facings. Out-of-stocks cost about 4 % of sales on the worldwide benchmark (Gruen, Corsten and Bharadwaj, GMA/FMI, 2002), and more than that in promoted or high-velocity categories.
7. Self-checkout shrink ratio. The new hero metric. SCO loss as a multiple of staffed-lane loss. Target: drive it toward 2× through computer-vision-aided detection. 1× is not a real target while the customer is still doing the scanning.
8. Staff-to-traffic ratio. Labor cost over foot-traffic volume. Video gives it real-time; workforce planning systems (UKG, Kronos, Legion) consume it for scheduling.
Capabilities: from people counting to planogram compliance
Retail video analytics is software that runs computer-vision models on a store’s existing camera feeds and turns what it sees into business metrics: foot traffic, conversion, queue depth, dwell time, planogram compliance, on-shelf availability and self-checkout loss. The output is numbers on a dashboard, not footage for a human to watch. It is a stack of computer-vision primitives rather than a single algorithm, and each primitive, like dedicated people counting software, can be a product in its own right. Practical capabilities in 2026:
| Capability | Primary model | Business function served | Privacy posture |
|---|---|---|---|
| People counting | Object detection (YOLO11 / YOLO26) | Traffic, conversion | Anonymous |
| Queue detection | Detection + ByteTrack / BoT-SORT tracking | Checkout staffing, abandonment | Anonymous |
| Dwell time / heatmap | Multi-object tracking | Merchandising, store layout | Anonymous aggregate |
| Planogram compliance | Shelf segmentation + OCR | Merchandising, category management | No personal data |
| On-shelf availability | Shelf segmentation + classification | Supply chain, store ops | No personal data |
| Self-checkout loss detection | Pose estimation + scan-sync model | Loss prevention at SCO | Skeleton-based (no face) |
| LP anomaly flags | Pose + behavior classification | LP investigations, ORC detection | Skeleton-based (no face) |
| Anonymized demographics | Age / gender bracket estimation | Marketing, assortment planning | Aggregate only; BIPA-sensitive |
The privacy posture column matters more than most retailers realize. Facial recognition, even for “known shoplifter” lists, trips BIPA in Illinois and is banned in several US cities. Skeleton- and keypoint-based analytics sidestep most of it.
The self-checkout problem and how CV actually helps
Self-checkout loss multiples vary wildly by study and by what is being measured. ECR Retail Loss’s 2026 data put SCO stores at 1.96 % shrink against 1.35 % for non-SCO stores (~1.45×); Grabango’s transaction-level study found a 3.5 % SCO shrink rate against 0.21 % at cashier lanes (16×). Where a given chain lands depends on the retailer, the category mix, and the SCO station design. We scope this per store: roughly $10–16 K of SCO-attributable loss per store per year at mid-market basket sizes. On that basis a 200-store chain with 40 % SCO penetration is carrying $2–$3.2 M annually, and the 50-store model further down this page carries $500–$800 K. Chains with higher baskets or heavier SCO penetration run well above that.
Computer-vision at the SCO lane doesn’t try to catch every skip-scan in real time. The better pattern:
1. Scan sync model. A camera at the bagging area watches items moving into the bag. A timing model compares the number and size of items bagged against the POS scan stream. Mismatch beyond a threshold triggers an attendant prompt or post-facto review flag.
2. Ticket-switch detection. Pose-based detection of hands near UPC labels, coupled with a category-level model that flags when a premium item’s label has been swapped for a lower-priced SKU.
3. Walk-off detection. Customer leaves the SCO zone with items but no completed transaction. Simple and effective; the model is a trip-line plus POS hook.
4. Attendant-prompt design. The feedback loop matters as much as the model. Prompts should be specific (“please re-scan the last item”), not accusatory, and should include a confidence-aware grace path. Operator trust is the product, not the raw accuracy.
Realistic outcome: a 60 % reduction in the SCO loss multiple (bringing a 5× baseline back toward 2×), with 6–9 month payback in most mid-market chains. Be clear about what that number is. A planning assumption drawn from deployment experience, not a controlled study. We haven’t published one and neither has anyone else. Re-measure it against your own pre-deployment baseline at the end of the first quarter and re-forecast.
Reach for CV scan-sync at self-checkout when: SCO is more than ~30 % of transactions and your SCO shrink runs above 3× staffed lanes — that’s where payback is fastest.
Planogram compliance and on-shelf availability
In our scoping calls retail ops leaders put 40–60 % of their stores out of planogram compliance at any given time. That is what practitioners tell us, not a published benchmark — missing facings, misplaced SKUs, promos not set. Weekly field audits partially close the gap; video analytics closes it continuously.
The technical approach: shelf cameras pointed at high-priority sections (impulse end-caps, promo zones, high-margin categories). Segmentation models divide the shelf into facings; classification models identify what’s there; OCR reads pricing and shelf tags. Deltas against the authoritative planogram fire alerts to the store manager and to the category team at HQ.
On-shelf availability is the same architecture with a different rule set: empty-facing detection with aggregation into an OOS list by SKU and zone. The OOS list feeds the handheld restock app staff already use, so there’s no new workflow to adopt.
Realistic impact: vendors and retailers report a 3–5 % category sales lift on fully-compliant sets (Trax and NielsenIQ deployments track 8–14 point compliance gains inside 12 months). Treat that as a vendor claim until you have measured your own baseline. On top of it sits a slice of the roughly 4 % of sales lost to out-of-stocks, the worldwide benchmark Gruen, Corsten and Bharadwaj measured for GMA/FMI in 2002 at an 8.3 % average OOS rate. Their consumer-response split is the part worth memorising: 31 % of shoppers buy the item at another store and 9 % don’t buy it at all, so 40 % of an out-of-stock is lost to you outright; the other 60 % substitutes or delays. A more recent 2020 consumer survey puts the walk-out share at 39 %. Payback lands in the 6–12 month window for mid-market chains, shorter in grocery where OOS economics are severe.
Architecture: edge inference per store, cloud aggregation for the chain
Retail bandwidth is the constraint that shapes the architecture. Strip-center stores often run a single consumer-grade WAN link; rural locations rely on 4G/5G bonded links. Shipping raw video over that backhaul is not an option at any serious scale. The default pattern we ship:
Per-store edge box. A Jetson Orin NX carries 4–8 retail cameras and an AGX Orin 10–16, depending on model mix. Derate hard from NVIDIA’s DeepStream 7.0 reference numbers (the current DeepStream 8.0 docs publish throughput tables for Jetson Thor only, so 7.x remains the Orin reference: 16 and 37 H.265 1080p30 streams on a ResNet18 detector plus IOU tracker at INT8, display off): shelf segmentation and pose estimation cost several times what TrafficCamNet does, and real RTSP fleets never hit lab throughput. Runs the full inference stack — detection, tracking, queue, shelf, SCO. Emits metadata: counts, dwell histograms, shelf compliance events, anomaly flags. Local NAS buffers 30–90 days of raw video for LP review.
ONVIF Profile M. Metadata rides ONVIF Profile M back to the VMS if one exists. More on ONVIF Profile M and the broader ONVIF profile family in our deep-dives.
Chain-level cloud aggregation. Per-store metadata streams into a cloud warehouse (Snowflake, BigQuery, or a purpose-built retail analytics SaaS). Dashboards for LP, ops, category management. The overnight job shipping video clips of confirmed incidents runs at 02:00–05:00 store time to avoid daytime bandwidth contention.
Real-time alerts stay local. Queue-depth alerts to store staff, SCO attendant prompts, OSA flags to the restock app — all originate at the edge. Cloud is the analytics layer, not the real-time control plane.
For the engineering detail of real-time inference on this stack see our real-time video processing best practices and the AI-for-video-engineering fundamentals in our Learn track.
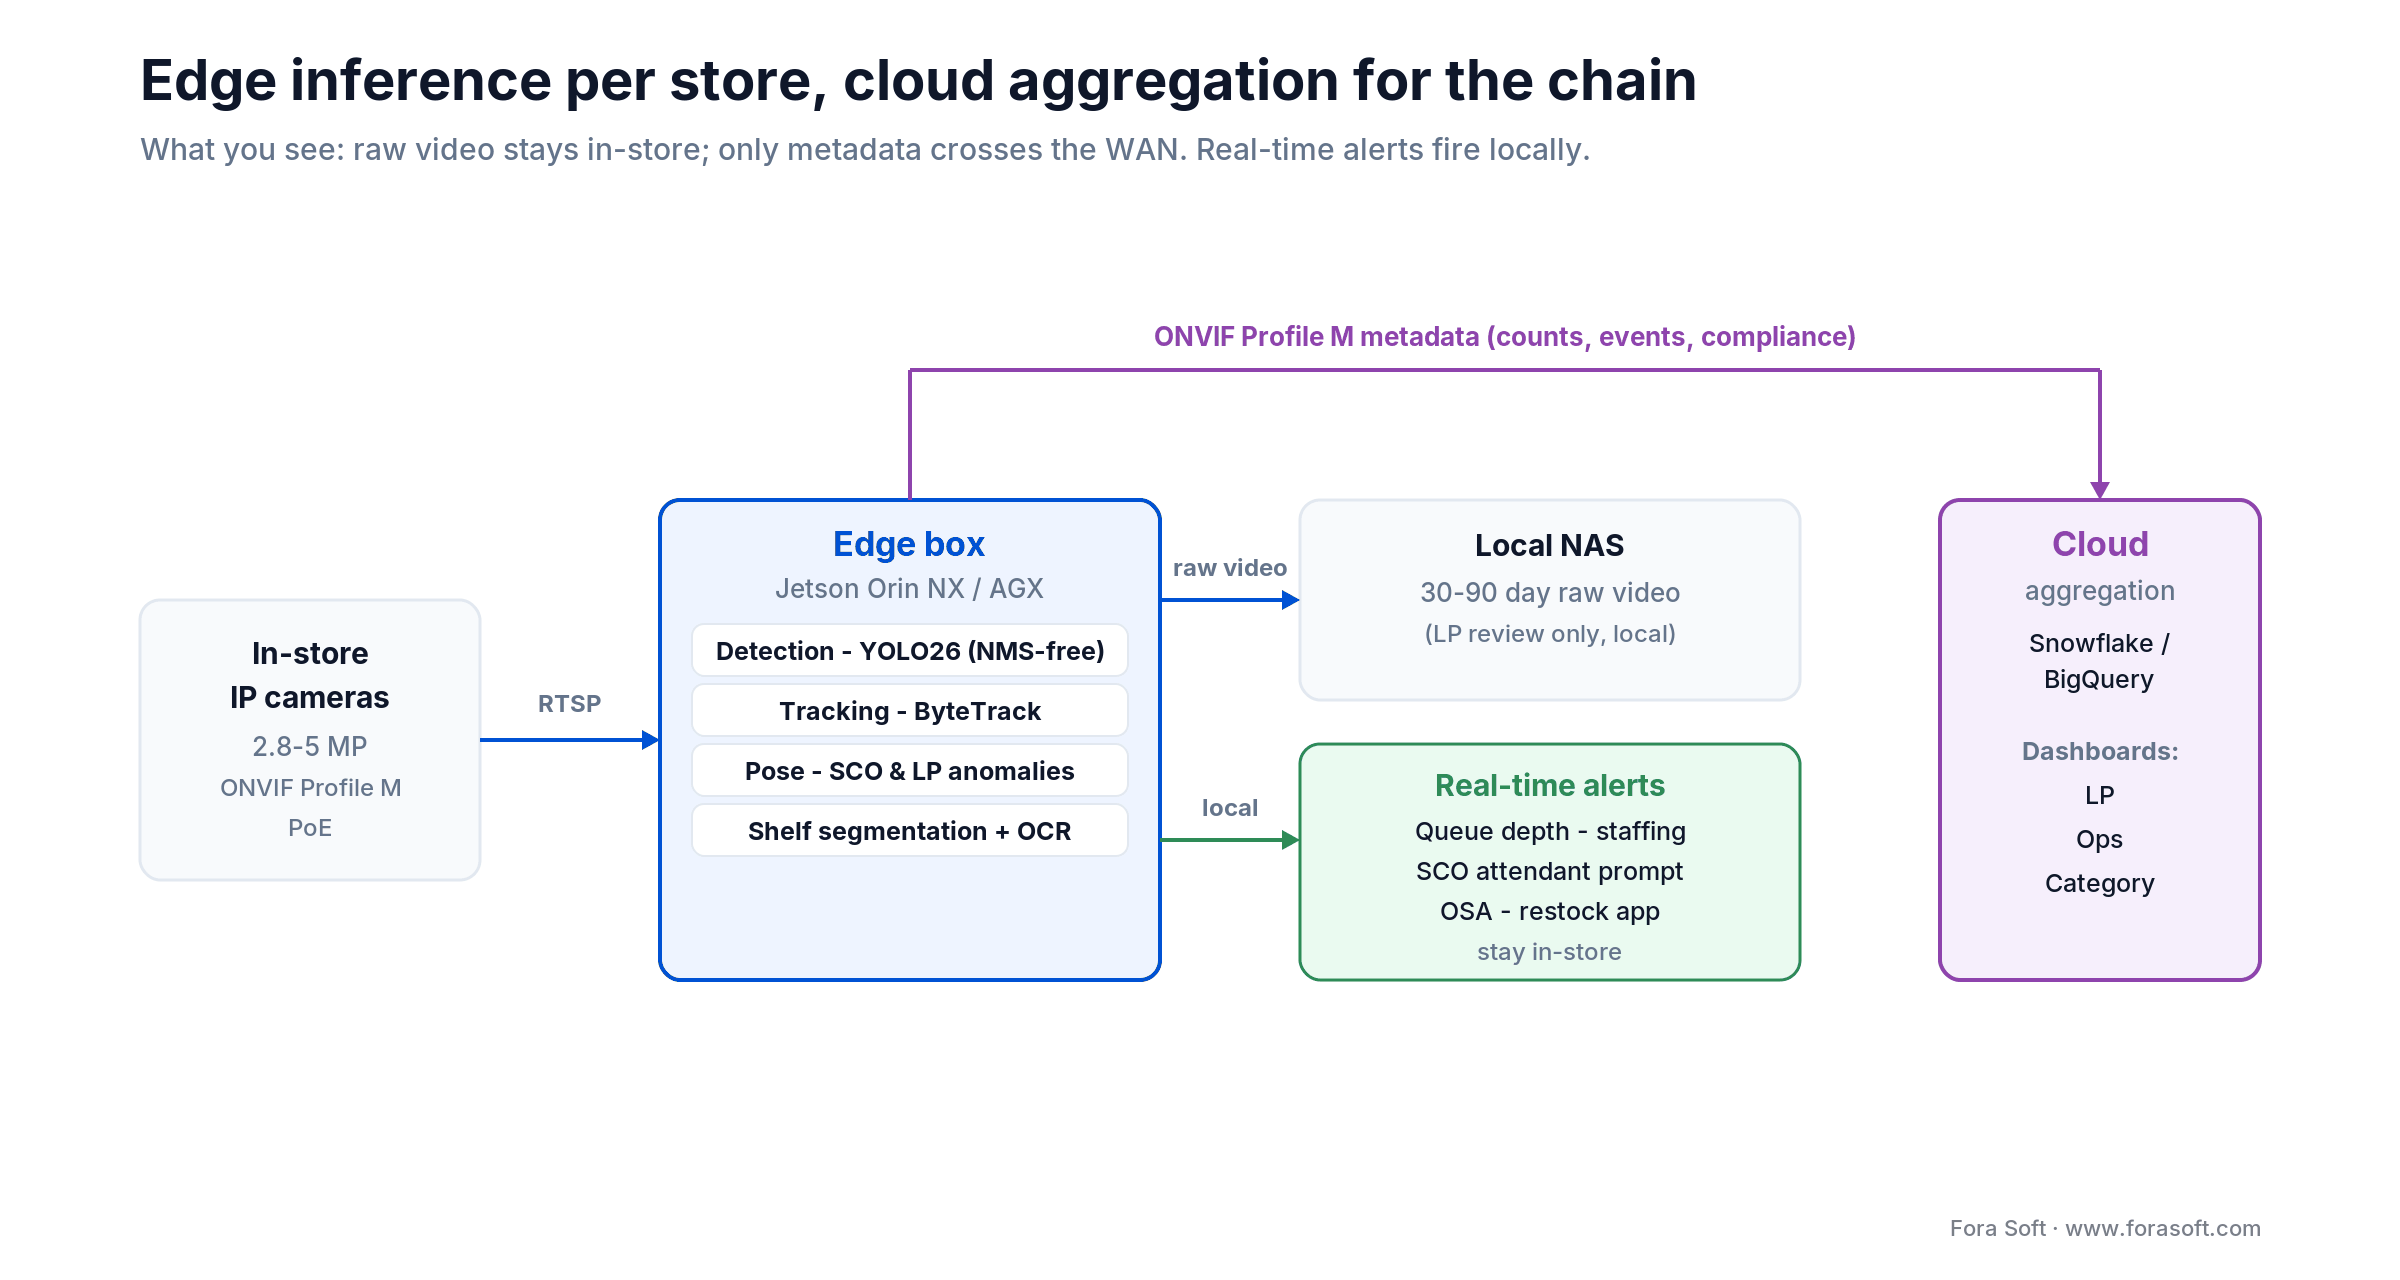
Figure 2. The default deployment: edge inference per store, only metadata over the WAN, real-time alerts fired locally.
Hardware: cameras and the edge box
Cameras. Mix of 2.8–5 MP IP cameras, ONVIF Profile M-capable, PoE-powered. Axis, Hanwha and Uniview all work; choose on service relationship and availability, not brand loyalty. Hikvision and Dahua sit on the FCC Covered List and are barred under NDAA §889 for federal agencies and their contractors. Still legal for most private retail, but they cannot obtain new US equipment authorizations, so treat them as a supply-and-support risk rather than a default. Since 16 July 2026 the FCC also bars importing and marketing previously authorised covered equipment for the listed public-safety, government-facility and national-security uses. Ordinary retail use falls outside those purposes and installed cameras can keep running, but the US channel for that gear keeps narrowing. Legacy analog cameras can feed an IP encoder but the resolution ceiling cripples shelf-level analytics — plan a refresh on the 30–40 % of cameras that need it most.
Edge box. The Jetson Orin family is the 2026 default. JetPack 6.2’s Super Mode (January 2025) lifted the whole family in firmware: Orin Nano 8 GB from 40 to 67 sparse-INT8 TOPS, Orin NX 16 GB from 100 to 157 — halve both for dense INT8, which is the number that matters for most retail models. The Orin Nano Super dev kit covers a kiosk’s 1–2 streams; Orin NX handles 4–8 retail cameras; AGX Orin 10–16. Price them at today’s list, not last year’s: in July 2026 NVIDIA raised Jetson prices by up to 101 % — the Orin Nano Super dev kit went from $249 to $399, the Orin NX 16 GB module from $599 to $999 and the AGX Orin 32 GB module from $899 to $1,799 (1,000-unit pricing). For the heaviest stores, the Thor-based Jetson T4000 ($2,999 since the same change) is the next step up, and NVIDIA announced smaller T3000 and T2000 modules in July 2026 for Q1 2027. YOLO26’s optional NMS-free graph (January 2026, up to 43 % faster CPU inference than YOLO11) packs more cameras onto each box. Hailo-8 is a viable lower-power alternative for detection-class workloads. Budget roughly $1,000–$3,500 per store for compute alone at October 2026 prices (an Orin NX module at minimum once a store runs 4+ cameras), depending on station count and module.
Rule of thumb for a typical 8-camera specialty retail store: one Jetson Orin NX or AGX, a PoE switch, a local NAS, and the software stack, at $5–$9 K of hardware before install and software. A 20–40-camera grocery or big-box store lands at $9–$13 K, which is the per-store figure the 50-store model below assumes.
POS, inventory, workforce: integrations that make analytics actionable
Video analytics without POS integration is a dashboard. Video analytics with POS, inventory, and workforce integration is a decision system. The integrations we wire on every retail project:
POS. NCR Voyix, Oracle Retail Xstore, Square / Block, Shopify POS, plus Toast and Oracle MICROS Simphony on the F&B-adjacent side. The transaction stream gives you the conversion-rate denominator and the SCO scan-sync signal. Most have REST or webhook APIs; older NCR installs ship flat-file exports.
Inventory / merchandising. SAP Retail, Oracle Retail, Blue Yonder (formerly JDA), Relex. Planogram master data and SKU lists flow into the shelf-compliance model; OSA events flow back for replenishment planning.
Workforce / scheduling. UKG (Kronos), Legion, Zebra Workcloud (the former Reflexis suite; Zebra bought Reflexis in September 2020 and rebranded it). Queue depth and foot-traffic data feed intraday staffing adjustments; dwell and conversion feed weekly schedule optimization.
LP case management. Appriss Retail, LP Innovations, internal Zendesk / ServiceNow queues. Anomaly alerts become investigation cases with video clips attached.
Plan 2–4 weeks per integration for the first pass, half that on the second retailer. The integration work is the bulk of the “soft” project cost.
Building a retail analytics product and need a POS/ONVIF integration partner?
We build the integration layer for video-analytics products shipping into retail. 30 minutes, concrete integration plan, no sales pitch.
Retail-first platforms vs. general VMS: where to buy, where to build
Two vendor categories dominate the market. They solve different problems and retailers routinely make the wrong choice.
General VMS platforms — Milestone XProtect, Genetec Security Center, Avigilon Unity Video (formerly Avigilon Control Center), Network Optix Nx Witness — are excellent for surveillance, LP review, and security operations. They’re poor at retail KPIs out of the box. Expect heavy plugin work to make them speak the language of conversion rate, dwell, and planogram compliance.
Retail-first analytics platforms — Solink, RetailNext, Everseen, Envysion, Hanwha Vision retail modules, AiFi, Standard AI (spatial analytics now: it sold GoSkip to PAR Retail in 2025 and bought Pathr.ai in January 2026) — ship with POS integrations, planogram templates, and dashboards aimed at category and ops leaders. They struggle to replace a full VMS for LP investigations; most retailers run both.
When to build. If you’re a retail-tech product company selling into retailers, “build” means building your own analytics layer on top of ONVIF / VMS plumbing. We ship this regularly as part of our computer vision development services — the client keeps product differentiation and we own the video-engineering layer. If your primary lens is loss prevention and security rather than merchandising KPIs, our companion guide to retail video surveillance covers that framing.
Reach for a retail-first SaaS when: you’re a retailer buying for your own chain, moderate customization, moderate timelines, no engineering team.
Reach for a general VMS + analytics plugin when: LP is the primary use case and you already have a VMS investment you can’t displace.
Reach for custom build when: you’re a retail-tech vendor, product differentiation matters, and you want to own the roadmap.

Figure 3. Buy, plug, or build — one decision trunk driven by engineering capacity, VMS lock-in, and product intent.
Privacy: BIPA, CCPA, GDPR, and the design choices that clear review
Retail privacy law is a patchwork. The design choices that clear almost all of it:
1. No face recognition by default. Use skeleton / keypoint analytics for behavior and pose-based detection for SCO and LP anomalies. BIPA still requires consent for any face template even after the 2024 damages cap, and Portland’s 2020 ordinance bans private entities outright from using face recognition in places of public accommodation (San Francisco’s 2019 ordinance binds city departments, not retailers) — so don’t build a face-print database unless you have an explicit consent workflow and the legal headroom to run it.
2. Anonymized demographic brackets only. Age / gender estimation as aggregated brackets (18–34, 35–54, 55+) for marketing signal. Never tied to a specific person, never persisted against an identity. Know where this sits in EU law, because plenty of vendor decks get it wrong: inferring age or gender is biometric categorisation, but the Commission’s own guidance says age and gender are not sensitive or protected attributes, so it is neither prohibited under Article 5 nor high-risk under Annex III. Emotion recognition is a different matter and does land in Annex III. Article 50(3) still bites, though: if you deploy a biometric categorisation system you have to tell the people exposed to it, and that duty has applied since 2 August 2026. GDPR applies to all of it on its own terms on top of that.
3. Metadata-first storage. Store counts, dwell histograms, events. Retain raw video only for 30–90 days and only where LP needs it. Delete clips not attached to confirmed incidents on schedule.
4. On-device inference. Run detection / tracking / pose at the edge. Keep personal data resident in-store; ship only aggregated metrics to the cloud. Clean GDPR story; cleaner BIPA story.
5. Signage, DPIA, DPA. Standard camera-notice signage at entrances; a customer-facing privacy note on the retailer’s website; DPAs in place with every cloud processor. For EU stores run a DPIA before go-live. Systematic monitoring of a publicly accessible area is on the EDPB’s Article 35 list, so it is mandatory, not optional. The lawyers will ask; have the answer in advance.
Cost and ROI for a 50-store chain
Ballpark economics to anchor a business case for a 50-store specialty or grocery chain:
| Line item | Year 1 | Year 2+ (per year) |
|---|---|---|
| Cameras + edge hardware (50 stores) | $450 K–$650 K | ~$40 K replacement / refresh |
| Software licensing / SaaS | $100 K–$200 K | $100 K–$200 K |
| Integration + install | $100 K–$200 K | — |
| Ops / tuning / calibration | $50 K–$100 K | $40 K–$80 K |
| Total | $700 K–$1.15 M | ~$180 K–$320 K / year |
Benefit-side, conservatively stacked:
- Shrinkage reduction (a conservative 0.06 pts on a $300 M network, well under the 0.2–0.4 pts the pipeline can reach): ~$180 K / year.
- SCO loss reduction (60 % of a $500 K–$800 K exposed baseline): $300 K–$480 K / year.
- Queue abandonment reduction (2–3 pts of checkout friction): $75 K–$150 K / year.
- Planogram / OSA lift (share of 3–5 % category sales lift): $150 K–$300 K / year.
Stacked conservatively, a 50-store retail video analytics rollout returns $705 K–$1.11 M of annual benefit against $700 K–$1.15 M of year-one cost, which is an 11–15 month payback (matched low and high cases both land near 12 months; the band allows for uneven ramp-up across stores). The hardware line already carries NVIDIA’s July 2026 Jetson price rise; on 2025 list prices the same plan paid back about a month sooner. That window is realistic for specialty and grocery; drug / convenience often faster because shrinkage baselines are higher.

Figure 4. A conservative 50-store business case: stacked annual benefit clears Year-1 cost in about 11–15 months.
Mini-case: retail analytics layered onto a multi-site VMS deployment
Situation. A security integrator working with a multi-site specialty retailer wanted to layer retail-specific analytics — people counting, dwell, queue, SCO loss, shelf compliance — onto an existing VMS deployment without ripping out cameras or disrupting LP workflows. Store managers were already overloaded; the new feature had to produce fewer alerts, not more.
12-week plan. Weeks 1–2: camera audit across two pilot stores, labelled 30 days of recorded video per store, baseline “normal” per camera position. Weeks 3–5: Jetson AGX Orin edge box per store, YOLO26-based detection + BoT-SORT tracking + pose estimation, ONVIF Profile M metadata publisher, per-store dashboard. Weeks 6–7: VMS plugin integration (Milestone XProtect), POS tie-in for conversion and SCO scan-sync, LP alert webhook. Weeks 8–10: calibration pass — shadow suppression, camera-vibration filter, zone-specific thresholds, weekly retraining loop on SCO patterns. Weeks 11–12: staged rollout behind a feature flag, store-manager training, quarterly re-baselining runbook.
Outcome. The retailer’s own SCO loss figures are theirs to publish, not ours, so here is what we can put a number on. False alarm rate on behavioral anomalies dropped from 6–8 per camera per day in week one to under 1 per camera per day after the calibration pass. Planogram compliance scoring moved from quarterly manual audits to a daily dashboard metric. Rollout expanded to the wider store network the following quarter. It’s the same edge-analytics pattern behind Valt, our surveillance product now running across 770+ US organizations and 50,000+ users.
A decision framework — five questions before you scope
1. What’s the leading KPI? Shrinkage → LP-focused stack with pose-based anomaly detection. Conversion / staffing → queue and traffic-focused stack. Category sales → shelf and planogram-focused stack. Don’t try to ship all three at once.
2. Buy a retail-first SaaS, plug a VMS, or build custom? Retailers with < 50 stores and no engineering team buy retail-first SaaS. Retailers with an existing VMS investment add an analytics plugin. Retail-tech vendors and chains > 500 stores build custom for differentiation and per-store economics.
3. What’s the privacy envelope? Illinois presence → skeleton analytics, no face. EU stores → on-device inference, DPA with every cloud processor. Portland stores → no face recognition, period; San Francisco’s ban covers city departments, not private retail.
4. POS and inventory integration on day one, or phase two? For LP and operational KPIs, POS integration on day one. Planogram / OSA can wait for phase two unless category management is driving the buy.
5. Who owns the calibration? Each store needs 4–8 weeks of threshold tuning after install. Decide up front: internal LP / ops team, managed service from the vendor, or hybrid. Unowned calibration = failed deployment.
Five pitfalls that sink retail video-analytics projects
1. Applying lab benchmarks to production cameras. Models trained on curated datasets lose 10–20 points of accuracy on mixed-quality retail camera fleets. Plan site-specific fine-tuning from day one; treat the vendor demo as a ceiling, not a floor.
2. Demographic model bias. Age / gender estimators trained on limited populations underperform on non-Western demographics, darker skin tones, and older adults. Test on representative samples of your actual foot traffic; audit quarterly.
3. LP silo vs. operations silo. LP owns loss; ops owns staffing and merchandising; category owns shelf compliance. A single analytics platform that doesn’t reconcile the three silos gets blocked in procurement. Assemble a cross-functional steering committee before the vendor evaluation, not after.
4. Alert fatigue at the store level. More than a handful of daily alerts per store-manager and the channel gets muted. Tier severity, route operational alerts to ops and LP alerts to LP, show confidence bins instead of raw scores.
5. No retraining cadence. Store remodels, seasonal lighting changes, and product-mix shifts silently degrade model accuracy. Build a quarterly retraining loop into the ops runbook, not into the roadmap.
KPIs to track post-launch
Quality KPIs. People-count accuracy vs. door-counter ground truth (target ≥ 95 %). Queue-detection accuracy on weekly sampled video (target ≥ 90 %). SCO-flag precision (target ≥ 75 % — below that, attendant trust erodes).
Business KPIs. Shrinkage rate by store-quartile (target meaningful drop inside two quarters). SCO-shrink multiple vs. staffed-lane (target ≤ 2×). Planogram compliance score (target ≥ 85 % corporate-wide inside two quarters). Queue abandonment rate (target ≤ 1.5 %).
Adoption KPIs. Store-manager dashboard engagement weekly (target ≥ 80 % active). LP case-closure time (target shorter than pre-deployment baseline). Alert mute rate (target 0 %; mutes are silent product failures).
When NOT to ship retail video analytics yet
If your camera fleet is majority legacy analog and there’s no IP refresh on the roadmap, spend the money on cameras first. Analytics can’t compensate for inputs that lose the details that matter. If your LP and ops teams don’t coordinate today, analytics will widen the gap before it closes it — do the governance work first. If you’re about to roll out a new POS system, wait — the integration work you’d do now will get redone anyway. And if your privacy counsel is uncomfortable with on-camera analytics at all, that’s a signal to slow down and scope a narrower pilot, not to push through.
Ready to put a plan and a number on a retail-analytics rollout?
Bring your store count, your VMS / POS stack, your leading KPI, and your privacy envelope. In 30 minutes we’ll scope the stack, the cost, and a realistic 12-week plan.
Realistic 12-week timeline for a pilot
| Week | Workstream | Deliverable |
|---|---|---|
| 1–2 | Site survey + KPI alignment | Camera audit; labelled baseline clips; leading KPI confirmed |
| 3 | Privacy & compliance design | BIPA/CCPA/GDPR posture; signage plan; DPA draft |
| 4–5 | Edge inference stack | Jetson / Hailo edge box; detection + tracking + pose; ONVIF Profile M emitter |
| 6–7 | VMS + POS integration | Plugin / webhook; SCO scan-sync; conversion correlation |
| 8 | Shelf + planogram pipeline (optional) | Shelf segmentation; OSA alerts; planogram dashboard |
| 9 | Calibration pass | Shadow / vibration / lighting filters; per-zone thresholds |
| 10 | Dashboards & governance | Per-role dashboards; alert routing; steering-committee cadence |
| 11 | Staged rollout | Feature-flagged pilot stores; store-manager training |
| 12 | Runbooks & retraining loop | Quarterly re-baseline runbook; LP feedback loop; chain rollout plan |
Figure 5. A 12-week pilot lands a production-grade retail analytics feature in 1–2 stores. Chain rollout to 50 stores typically takes another 4–6 months depending on regional phasing.
FAQ
Do we need facial recognition to run effective retail video analytics?
No — and you almost certainly shouldn’t. Skeleton / keypoint analytics plus pose estimation handle people counting, dwell, queue, SCO monitoring, and LP anomalies. Anonymized age / gender bracket estimation gives marketing signal without identifying anyone. This combination passes BIPA, CCPA, GDPR, and the municipal facial-recognition bans with much less friction.
What’s the realistic payback period for a 50-store deployment?
11–15 months for specialty and grocery, faster (6–10 months) in drug and convenience where shrinkage baselines are higher. Shrinkage plus SCO loss typically carries the business case on its own; planogram / OSA / staffing KPIs are the phase-two upside.
Can we run this on top of our existing Milestone / Genetec VMS?
Yes, via an analytics plugin and ONVIF Profile M metadata. VMS handles LP review and recording; the analytics layer handles retail KPIs and dashboards. Expect 2–3 weeks of integration testing with the specific VMS version your chain runs.
How do we integrate with NCR, Oracle Xstore, or Square POS?
NCR Voyix and Oracle Retail Xstore expose event streams via their standard APIs; Square / Block via REST webhooks; older NCR installs often ship flat-file exports. The integration layer correlates foot traffic with transactions for conversion and basket-size metrics, and pairs SCO events with scan data. Budget 2–4 weeks for the first retailer, half that for subsequent rollouts on the same POS.
What’s the right retention policy for retail video?
30–90 days for raw video on local NAS, permanent retention for metadata (counts, dwell, compliance scores). Raw clips attached to confirmed LP incidents kept longer per legal hold. Delete everything else on schedule. This posture clears most regulator concerns at once.
Can legacy analog cameras feed the analytics pipeline?
Via an IP encoder, yes — but resolution ceilings (often 480p effective) cripple shelf-level analytics and SCO loss detection. In practice plan to refresh 30–40 % of the camera fleet targeting front-of-store, SCO zones, and high-value categories; keep legacy cameras for general coverage. Factor the refresh into budget and timeline.
What’s the relationship between retail video analytics and general anomaly detection?
Retail analytics uses many of the same primitives (detection, tracking, pose) but applies them to retail-specific problems: conversion, queue, planogram, SCO, shelf. General anomaly detection covers the broader set (intrusion, falls, crowd, weapons) and is the right frame for non-retail environments. Our companion real-world anomaly detection playbook covers the broader engineering.
How long does it take Fora Soft to ship a pilot?
10–14 weeks for a production pilot on 1–2 stores with a Fora Soft team running Agent Engineering tooling (AI agents doing the repetitive build work under senior review): site survey, edge hardware, VMS + POS integration, calibration, store-manager training, staged rollout. Chain expansion adds 4–6 months for a 50-store network depending on regional phasing.
How much does retail video analytics cost per store per month?
Plan on roughly $170–$330 per store per month for software and SaaS licensing at chain scale, plus $5–13 K of one-off camera and edge hardware per store at October 2026 prices. With hardware amortised over five years, a 50-store programme runs about $450–$750 per store per month from year two.
Is retail video analytics the same as retail analytics software?
No. Retail analytics software analyses transaction, inventory and e-commerce data; retail video analytics is the in-store camera layer that adds foot traffic, queue, dwell and shelf data. The two meet in the same data warehouse, where video supplies the visitor count that turns transactions into a conversion rate.
What are privacy-friendly options for AI shrink detection?
Choose systems that work on skeleton, keypoint and object data rather than faces, run inference on a box inside the store, keep raw video 30–90 days and longer only for confirmed incidents, and send only aggregated metrics to the cloud. Self-checkout scan-sync and walk-off detection need no biometric data at all.
What camera and analytics setup works for dark stores?
Dark stores need shelf and pick-accuracy analytics rather than shopper analytics: fixed 4 MP+ shelf cameras over high-velocity aisles for on-shelf availability, overhead cameras at packing stations to check picked items against the order, and the same edge-box pattern as a retail store. With no customers on the floor, the privacy constraints are mostly about staff, not shoppers.
What to read next
Surveillance
Real-World Anomaly Detection in Surveillance Videos
The engineering playbook for anomaly detection across retail, logistics, perimeter, and smart cities.
Real-time
Real-Time Anomaly Detection in Video Surveillance
Latency-sensitive inference patterns that apply directly to SCO loss and queue detection.
Protocols
ONVIF Profile M and Object Detection
The metadata protocol retail analytics rides through from edge box to VMS to dashboard.
Analytics
Real-Time Video Analytics: Business Applications
Adjacent applications (logistics, security, operations) that share the retail architecture.
Engineering
Real-Time Video Processing with AI: Best Practices
The underlying engineering patterns for the edge inference stack used in retail.
Ready to turn store cameras into a real decision system?
Retail video analytics in 2026 is a KPI engine first, a surveillance system second. The winning pattern is edge-first inference on Jetson-class hardware, ONVIF Profile M metadata into whichever VMS the retailer already trusts, POS integration on day one for conversion and SCO signals, and privacy-by-design architecture that clears BIPA, CCPA, GDPR, and the municipal facial-recognition bans without a special project. Start with shrinkage and self-checkout loss — they usually carry the business case on their own — then layer planogram compliance, on-shelf availability, queue management, and staffing optimization in phase two.
The teams that succeed here build the governance (LP, ops, category, privacy) before they evaluate vendors. They calibrate per-store for 4–8 weeks post-install instead of treating the launch as the finish line. And they measure alert-mute rate as closely as shrinkage rate, because a muted alert channel is a silent product failure. We’ve shipped this pattern into multi-site retail and retail-tech products; a production-grade pilot lands in 10–14 weeks, chain rollout in 4–6 months after that.

The book · Volume 6 of 7
AI for Video: A Complete Guide to Intelligence in Video Products: From Models and Inference to Computer Vision, Speech, Search, and Generative Video
People counting, self-checkout monitoring and planogram checks all come down to models that see a store shelf reliably. This volume goes deeper into the capabilities behind them: detection, tracking, segmentation and OCR, deployment topologies from edge to cloud, and the lifecycle of an AI feature from prototype to production. Written by Nikolay Sapunov, CEO at Fora Soft.
Read it on Amazon →Kindle & paperback · Fora Soft Video Engineering Handbook
Let’s scope your retail analytics rollout
Bring your store count, your VMS / POS stack, your leading KPI, and your privacy envelope. 30 minutes, concrete plan, no sales deck.

